Loading... Today
-- 0
-- 0
The Electrical Post
Indian Power Sector Review
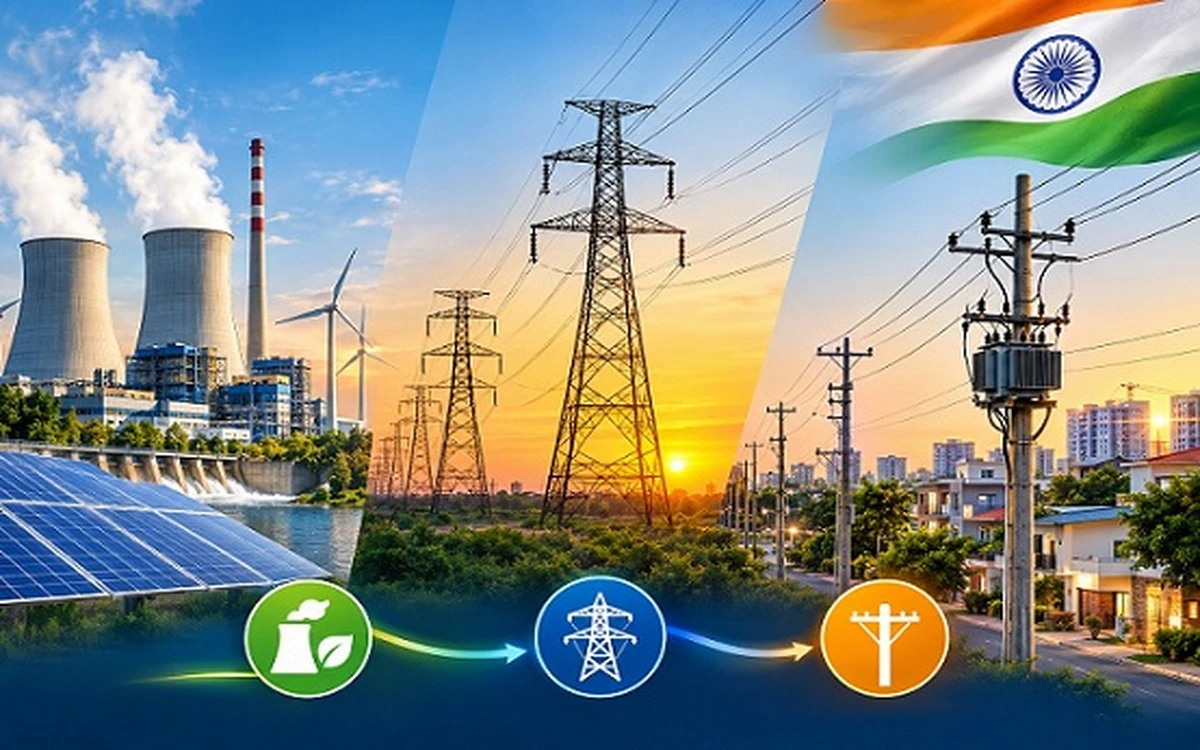
India’s power sector continues to play a pivotal role in enabling economic growth, industrial expansion, and improved quality of life, supported by sustained investments in generation capacity, grid modernisation, and clean energy transition. As one of the world’s largest producers and consumers of electricity, India is steadily moving towards a more diversified and sustainable energy mix, driven by supportive policy reforms, strengthening distribution discipline and accelerating renewable adoption. India's total installed power generation capacity reached 532.7 GW as of 31 March 2026, with a record capacity addition of 55.3 GW during FY 2025-26. Nonfossil sources accounted for 53.2% of the installed capacity, reflecting sustained momentum in the country's clean energy transition. While thermal power continues to provide critical base-load support and grid stability, increasing renewable integration is gradually reshaping the energy landscape towards a more balanced and resilient system.
Electricity demand continues to expand in line with economic activity, urbanisation, and rising electrification across industries and households, with India successfully meeting peak demand of ~242-243 GW in 2025. Industrial consumption remains the largest contributor, accounting for nearly 41-42% of total electricity usage, followed by residential, agricultural, and commercial segments, underscoring the close correlation between economic growth and power demand. To support this trajectory, transmission infrastructure continues to strengthen under the vision of “One Nation - One Grid - One Frequency,” with the national grid exceeding 5 lakh circuit kilometres and 1,407 GVA.
transformation capacity. Planned additions of ~67,000 circuit kilometres of transmission lines will further enhance inter-regional connectivity and facilitate the evacuation of renewable energy targeted at 500 GW by 2030.
The evolving power ecosystem reflects a steady shift toward cleaner and more efficient energy systems, with solar and wind leading capacity additions, supported by favourable economics, policy support, and growing private sector participation. Hydro, nuclear, and biomass continue to play an important role in balancing grid variability, while investments in green energy corridors, hybrid renewable zones, storage solutions, and emerging technologies such as green hydrogen are expected to further strengthen reliability and flexibility. Together, these developments position India’s power sector for sustained, efficient, and sustainable growth, enabling the creation of a future-ready energy infrastructure.
Outlook:
The Indian power sector is undergoing a significant transformation, driven by rising electricity demand, evolving energy mix, and changing market dynamics. India continues to focus on ensuring reliable power access while accelerating the transition towards cleaner energy through reduced dependence on fossil fuels and increased renewable capacity. Strong demand fundamentals, supportive policies, and sustained infrastructure investments are expected to drive future growth. By FY2030, the share of renewable energy in generation is expected to rise from 18% to 44%, while thermal power contribution may decline from 78% to 52%.
Overall, the sector is expected to remain a key enabler of economic growth by supporting rising electricity demand, strengthening energy security, and improving the resilience and sustainability of India’s power infrastructure.
Indian Power Distribution and DISCOM Reforms
India’s power distribution segment remains a critical pillar of the electricity ecosystem, ensuring reliable delivery of power to consumers amid rising demand driven by industrial growth, urbanisation, and increasing electrification. Improving the operational efficiency and financial sustainability of DISCOMs continues to be a major policy priority, particularly given longstanding challenges such as high Aggregate Technical and Commercial (AT&C) losses, tariff revision delays, and the gap between Average Cost of Supply (ACS) and Average Revenue Realised (ARR).
To address these issues, the Revamped Distribution Sector Scheme (RDSS), with an outlay of `3.03 lakh crore from FY2021–22 to FY2025–26, has accelerated infrastructure modernisation, loss reduction, and billing efficiency improvements. Initiatives such as smart metering, feeder segregation, and deployment of SCADA, ADMS, and GIS technologies are enhancing operational visibility, grid reliability, and system control. The Draft National Electricity Policy (NEP) 2026 further reinforces the focus on smart grids, renewable integration, and higher-voltage distribution systems to strengthen network efficiency and capacity.
India’s Clean Energy Transition
India’s energy transition is accelerating, supported by strong policy measures, ambitious targets, and sustained investments in clean energy infrastructure. The Government’s goal of achieving 500 GW of non-fossil fuel capacity by 2030 highlights the country’s shift towards a cleaner and more diversified energy mix. As of 31 March 2026, India’s installed renewable energy capacity stood at approximately 274.68 GW, led by solar and wind power.
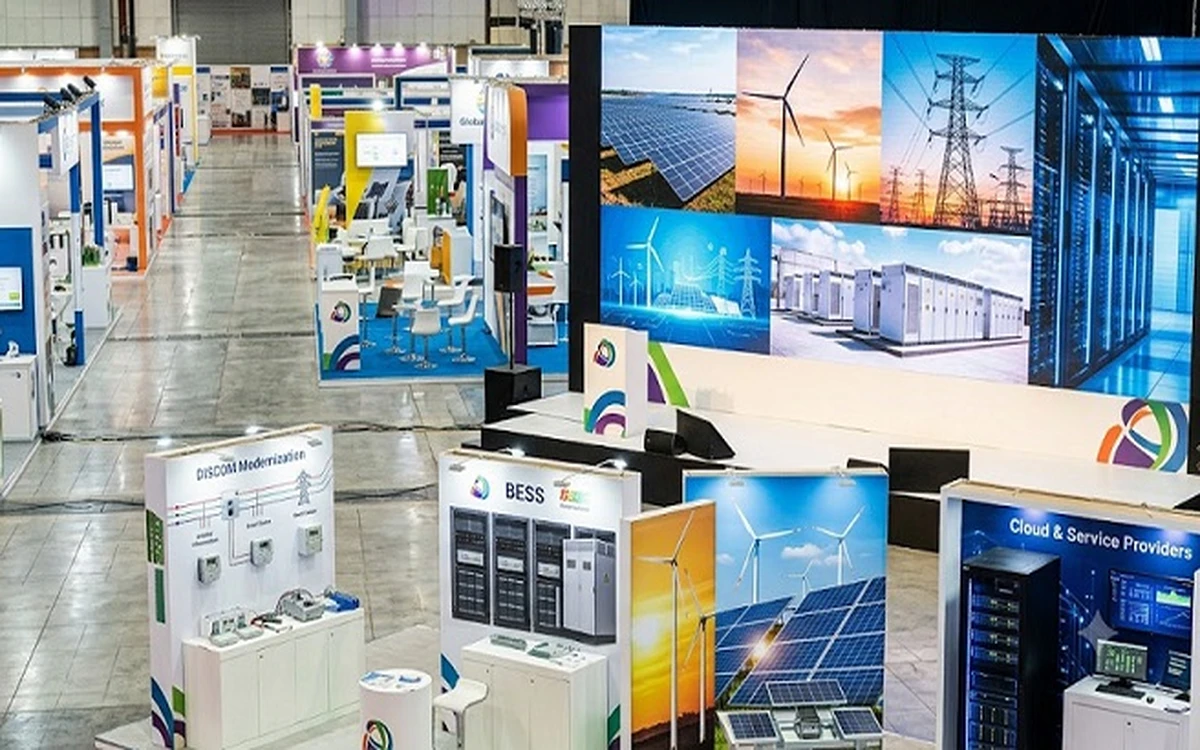
Strengthening grid infrastructure through initiatives such as the Green Energy Corridor remains critical for efficient renewable integration. At the same time, energy storage systems and digital grid technologies are becoming increasingly important for managing intermittency, improving flexibility, and enhancing system reliability. Beyond power generation, initiatives such as the National Green Hydrogen Mission are supporting industrial decarbonisation and the development of a broader clean energy ecosystem, accelerating India’s transition towards a low-carbon and resilient energy future.
India’s Infrastructure Sector
India’s infrastructure sector continues to play a pivotal role in driving economic growth, supported by strong policy measures, rising investments, and increasing private participation. Programmes such as PM Gati Shakti are accelerating integrated infrastructure development across transportation, logistics, power systems, and urban infrastructure, with a growing focus on sustainability, efficiency, and resilience.
The railway sector is witnessing significant transformation through electrification, network modernisation, and capacity expansion under the National Rail Plan 2030, which targets 100% electrification and higher freight modal share. Expansion of Vande Bharat trains and metro rail networks is strengthening passenger mobility and supporting sustainable urban transportation. India's operational metro rail network expanded to more than 1,155 km across 26 cities in 2026, reinforcing the country's position as home to the world's thirdlargest metro network and reflecting sustained investments in urban mass transit infrastructure.
Indian Mobility Sector
India’s mobility sector maintained strong momentum in FY 2025–26, supported by economic growth, infrastructure expansion, and rising consumption. The Indian automobile industry recorded its highest-ever annual domestic sales in FY 2025-26, with total vehicle wholesales reaching 28.27 million units, up 10.4% year on year. All major vehicle segments, including passenger vehicles, commercial vehicles, three-wheelers and two-wheelers, achieved record annual sales, reflecting broad-based growth across the industry.
Infrastructure development continued to play a critical role, with sustained investments in highways, expressways, and freight corridors improving connectivity and logistics efficiency across key economic regions.
Electrification is emerging as a structural trend, supported by government initiatives such as the Faster Adoption and Manufacturing of Electric Vehicles (FAME) scheme and the Production Linked Incentive (PLI) scheme, with strong growth in electric two- and three-wheelers. In parallel, the increasing adoption of digital technologies, including connected vehicles and telematics, is enhancing performance monitoring, enabling predictive maintenance, and improving overall operational efficiency.
Together, these trends are driving the evolution of India’s mobility ecosystem toward more efficient, technologyenabled, and sustainable transportation solutions.
India’s Battery Energy Storage System (BESS) Market
India’s Battery Energy Storage System (BESS) market is emerging as a key enabler of the country’s clean energy transition, supporting the rapid expansion of solar and wind capacity. As renewable generation increases, energy storage is becoming essential for managing intermittency, enhancing grid stability, and enabling reliable round-the-clock power supply.
During FY 2025-26, the BESS ecosystem gained further momentum, supported by favourable policy measures and a growing project pipeline. The Government of India’s Viability Gap Funding (VGF) scheme, with an outlay of `3,760 crore, aims to support the development of 13,200 MWh of storage capacity, improving project viability and encouraging private sector participation.
According to the National Electricity Plan, India’s energy storage requirement is projected to rise significantly from 82.37 GWh in FY 2026-27 to 411.4 GWh by FY 2031-32. With declining battery costs, technological advancements, and increasing adoption across grid balancing, peak demand management and renewable integration, BESS is set to play a critical role in strengthening grid flexibility and supporting India’s long-term clean energy ambitions.
India’s Electric Vehicle (EV) Infrastructure
India’s electric vehicle ecosystem expanded steadily in FY 2025–26, driven by policy support, rising investments, and growing consumer adoption. EV registrations crossed 2.45 million units, reflecting ~24–25% year-on-year growth, with penetration increasing to ~8.5% from 7.7% in the previous year. Growth continued to be led by electric two- and three wheelers, while passenger EV adoption gained momentum.
Charging infrastructure also scaled up across urban centres, highways, and commercial hubs, supported by investments from utilities, oil marketing companies, and private operators. The rollout of fast charging, battery swapping, and smart charging solutions improved accessibility.
Adoption is expanding beyond metros into Tier 2 and Tier 3 cities, aided by better infrastructure, wider product availability, and supportive state policies. Ongoing advancements in battery technology, charging networks and integration with renewable energy are expected to further accelerate India’s transition to sustainable mobility.
India’s Semiconductor Market
India’s semiconductor market gained strong momentum in FY2025–26, driven by rising demand across consumer electronics, telecom, automotive electrification, data centres, and industrial automation. India is among the world's fastest-growing semiconductor markets, with domestic semiconductor demand projected to reach approximately USD 90 billion by FY2030, driven by rapid growth in electronics manufacturing, automotive electrification, data centres, AI and digital infrastructure. The Government is accelerating ecosystem development through the Semicon India Programme under the India Semiconductor Mission (ISM), backed by an incentive outlay of around USD 10 billion. The initiative aims to strengthen capabilities across fabrication, ATMP, and chip design, while partnerships between global and domestic players are supporting the establishment of semiconductor manufacturing and packaging facilities. India’s strong semiconductor design talent base remains a significant advantage.
Supported by policy incentives, supply chain diversification, and rising investments, India is steadily emerging as a key hub for semiconductor design, manufacturing, and advanced electronics production.
India’s Cloud and Service Providers Industry
India’s cloud and service providers industry witnessed strong growth in FY2025–26, driven by rapid digital transformation, rising data consumption, and increasing adoption of AI, analytics, and IoT technologies. Enterprises across sectors are increasingly shifting to cloud-based infrastructure to improve scalability, flexibility, and operational efficiency. India’s public cloud market is projected to exceed USD 17–18 billion by 2027, supported by growing adoption across BFSI, retail, healthcare, telecom, and manufacturing.
Significant investments by hyperscale cloud providers in data centre infrastructure across major hubs such as Mumbai, Chennai, Hyderabad, Bengaluru, and Delhi NCR continue to strengthen the ecosystem. Government initiatives including Digital India, 5G expansion, and rising generative AI workloads are further accelerating demand for high-performance computing infrastructure. Increasing focus on renewable energy sourcing and energy-efficient operations is also driving sustainable growth across the sector.
2 days ago
Total Views : 51
2 weeks ago
Total Views : 114
2 weeks ago
Total Views : 72
2 weeks ago
Total Views : 138
3 weeks ago
Total Views : 97
3 weeks ago
Total Views : 150
last month
Total Views : 147
last month
Total Views : 67
last month
Total Views : 368
last month
Total Views : 230